Mutual Fund Taxation in India – Complete Guide
November 6th, 2026 News
Mutual Fund Taxation in India: Complete Guide for Investors
Introduction
Mutual funds are one of the popular investment options for individuals who want to grow their wealth, achieve financial goals and build long-term financial security. Whether you are a salaried employee, business owner or first-time investor, mutual funds offer different investment opportunities based on your financial requirements and risk appetite.
However, investing in mutual funds is not just about earning returns. Understanding Mutual Fund Taxation in India is equally important because the profits you earn may be subject to capital gains tax.
Different mutual fund categories have different taxation rules depending on their investment structure, holding period and purchase date. Knowing these rules can help you make informed investment decisions and plan your withdrawals efficiently.
In this blog, we will explain mutual fund taxation in India, including short-term capital gains, long-term capital gains, equity funds, debt funds, ELSS and dividend taxation.
What Is Mutual Fund Taxation in India?
Mutual fund taxation refers to the tax applicable to profits earned from mutual fund investments when investors redeem or sell their units.
The tax treatment generally depends on three important factors:
-
Type of mutual fund scheme.
-
Holding period of the investment.
-
Applicable income tax provisions.
Before understanding taxation, it is useful to understand 🟨 WHAT IS A MUTUAL FUND? and how different mutual fund categories work.
Generally, capital gains are classified into two categories:
1. Short-Term Capital Gains (STCG)
Short-term capital gains refer to profits earned when mutual fund units are sold within the applicable short-term holding period.
2. Long-Term Capital Gains (LTCG)
Long-term capital gains refer to profits earned when mutual fund units are sold after completing the applicable long-term holding period.
Taxation on Equity Mutual Funds in India
Equity mutual funds primarily invest in shares of companies. For tax purposes, an equity-oriented mutual fund generally needs to satisfy the prescribed domestic equity investment criteria.
Equity mutual fund taxation depends on how long you hold your investment.
Short-Term Capital Gains on Equity Mutual Funds
If you redeem eligible equity-oriented mutual fund units within 12 months of investment, the profit is generally treated as short-term capital gains.
-
Tax rate: 20%
-
Holding period: 12 months or less.
-
Applicable surcharge and cess may increase the final tax liability.
Example of STCG Tax Calculation
Suppose you invest ₹1,00,000 in an equity mutual fund and redeem it after 8 months for ₹1,25,000.
Your capital gain will be:
-
Investment amount: ₹1,00,000
-
Redemption value: ₹1,25,000
-
Profit: ₹25,000
-
Tax at 20%: ₹5,000
The above calculation excludes applicable cess and surcharge.
Long-Term Capital Gains on Equity Mutual Funds
If you hold eligible equity mutual fund units for more than 12 months, the profit is generally classified as long-term capital gains.
-
Tax rate: 12.5%
-
Annual exemption: ₹1.25 lakh on eligible aggregate gains.
-
Holding period: More than 12 months.
Example of LTCG Tax Calculation
Suppose your eligible long-term capital gains from equity mutual funds during a financial year are ₹2,00,000.
Your taxable gains will be:
-
Total capital gains: ₹2,00,000
-
Annual exemption: ₹1,25,000
-
Taxable gains: ₹75,000
-
Tax at 12.5%: ₹9,375
This exemption is an aggregate annual limit for eligible gains under the applicable equity-oriented fund capital gains provisions, not a separate exemption for every mutual fund.
Taxation on Debt Mutual Funds in India
Debt mutual funds invest primarily in fixed-income instruments such as government securities, corporate bonds and money market instruments.
Their taxation depends on the acquisition date and whether the scheme falls under the specified mutual fund definition.
Tax Rules for Specified Debt Mutual Funds
Under Section 50AA of the Income-tax Act, gains from specified mutual funds acquired on or after 1 April 2023 are generally treated as short-term capital gains and taxed according to the investor's applicable income tax slab.
From FY 2025–26, the definition of specified mutual funds was revised. Broadly, it covers funds investing more than 65% of their proceeds in debt and money market instruments and qualifying funds investing at least 65% in such funds.
For other debt-oriented funds that do not fall under these provisions, normal capital gains rules may apply depending on the acquisition date and holding period.
Therefore, investors should check the scheme classification before making redemption decisions
Taxation on Hybrid Mutual Funds
Hybrid mutual funds invest in a combination of equity and debt instruments.
Their tax treatment depends on the proportion of equity investment and the applicable tax classification.
-
Equity-oriented hybrid funds: Generally follow equity mutual fund taxation if they satisfy the prescribed criteria.
-
Other hybrid funds: May follow non-equity mutual fund taxation depending on their classification and acquisition date.
Investors should understand the scheme's asset allocation before choosing a hybrid mutual fund.
ELSS Mutual Funds and Tax Benefits
Equity Linked Savings Schemes (ELSS) are tax-saving mutual funds that primarily invest in equity markets.
They are commonly considered by investors who want to combine long-term wealth creation with tax planning.
Key Features of ELSS Mutual Funds
-
Minimum lock-in period of 3 years.
-
Eligible investments can qualify for deductions up to ₹1.5 lakh under Section 80C.
-
Market-linked returns.
-
Suitable for investors who understand equity market risks.
Are ELSS Investments Eligible Under the New Tax Regime?
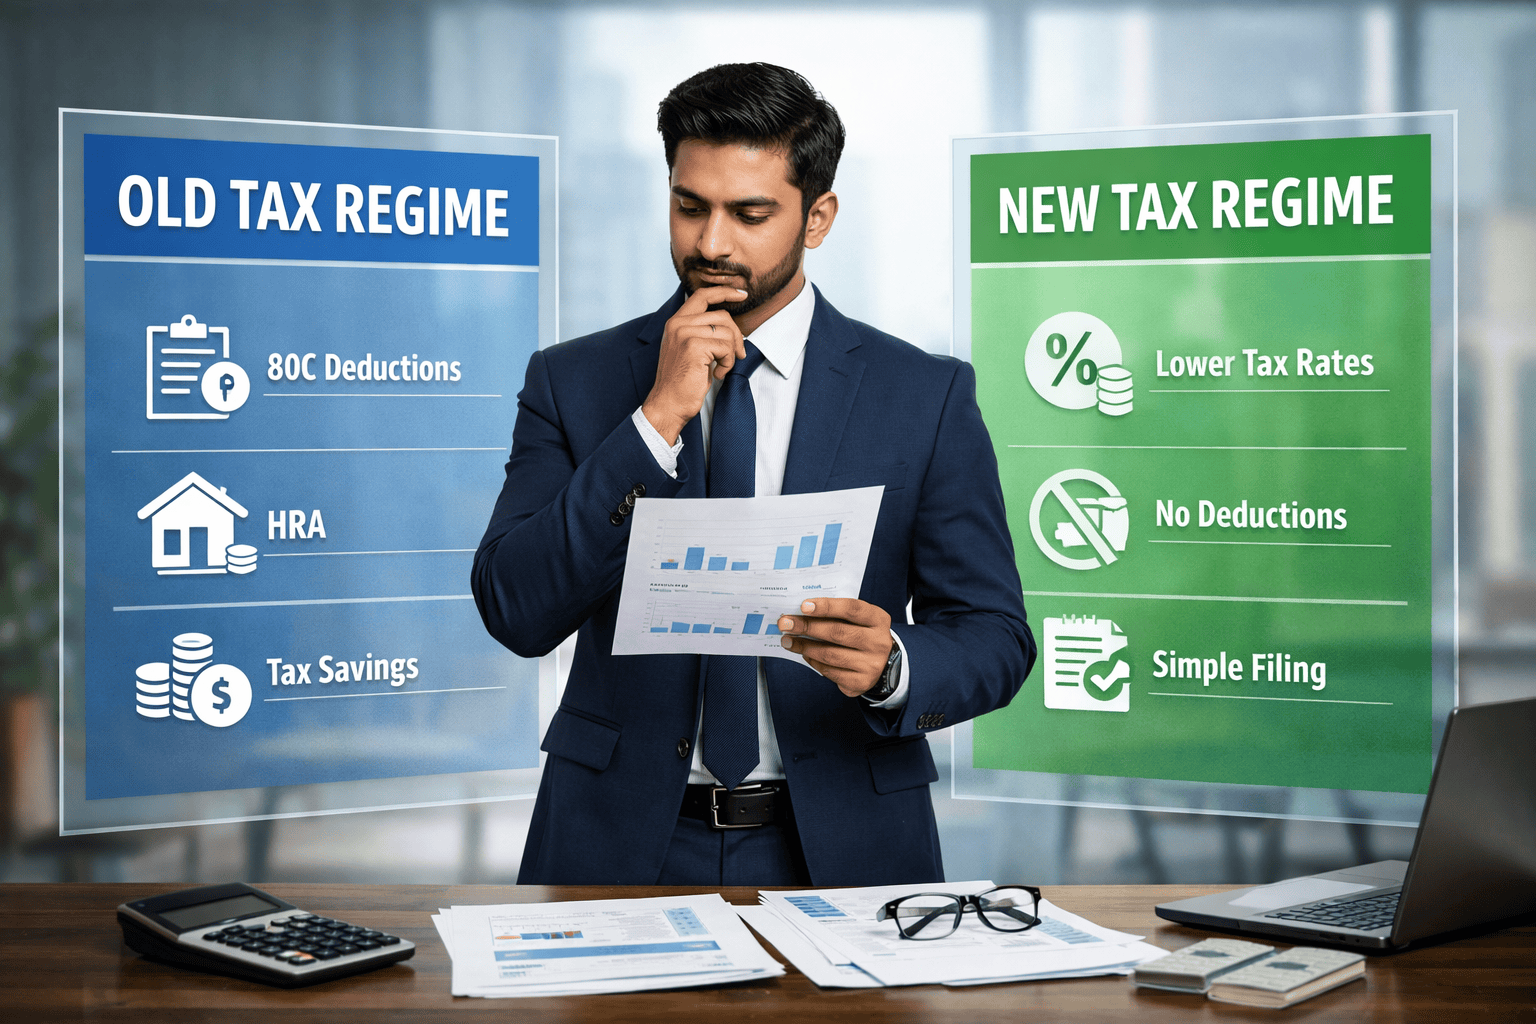
The Section 80C deduction is generally available under the old tax regime, subject to applicable conditions. It is not available under the new tax regime.
Investors should compare both tax regimes before choosing ELSS solely for tax-saving purposes.
Dividend Taxation on Mutual Funds
Mutual funds may distribute income through the Income Distribution cum Capital Withdrawal (IDCW) option.
Under the current taxation framework, IDCW income is generally taxable in the hands of investors according to their applicable income tax slab.
TDS on Mutual Fund Dividends
Under the applicable TDS provisions, tax may be deducted from eligible mutual fund income when the prescribed threshold is crossed.
For resident investors, the general TDS rate under Section 194K is 10%, subject to applicable conditions.
TDS is not necessarily your final tax liability. The actual tax depends on your total taxable income and applicable tax provisions.
How Can You Manage Your Mutual Fund Tax Liability?
Understanding taxation before investing can help you make more informed financial decisions.
Here are some useful considerations:
1. Invest According to Your Financial Goals
Choose mutual funds based on your investment horizon, financial goals and risk appetite rather than selecting a scheme only because of its tax treatment.
2. Understand Your Holding Period
Equity mutual funds have different short-term and long-term tax rates. Understanding holding periods before redeeming units can help you plan withdrawals.
3. Consider ELSS for Tax Planning
Investors following the old tax regime can explore ELSS investments for eligible tax deductions while considering the associated market risks and lock-in period.
4. Plan Your SIP Investments
Every SIP instalment is treated as a separate investment for calculating its holding period. Therefore, redemption may involve different tax treatments for different instalments.
If you are a salaried investor, read our guide on 🟨 DO SALARIED EMPLOYEES NEED A MUTUAL FUND SIP PLANNER IN FARIDABAD? to understand how structured SIP planning can support your financial goals.
5. Take Professional Investment Guidance
A mutual fund professional can help you understand different investment categories, portfolio allocation and redemption considerations.
Not sure whether mutual funds are suitable for your financial situation? Read our guide on 🟨 WHO SHOULD INVEST IN MUTUAL FUNDS? to understand how different investors can approach mutual fund investing.
For detailed tax calculations, consult a qualified tax professional.
Frequently Asked Questions.
1. What is the tax rate on equity mutual funds in India?
Eligible short-term capital gains are generally taxed at 20%, while eligible long-term capital gains are taxed at 12.5% on aggregate annual gains exceeding ₹1.25 lakh.
2. Are mutual fund returns tax-free in India?
No. Mutual fund capital gains and IDCW income may be taxable depending on the fund category, holding period and applicable tax provisions.
3. Is SIP investment taxable?
Yes, gains from SIP investments may be taxable when units are redeemed. Each SIP instalment has its own purchase date and holding period.
4. Is ELSS a good option for tax saving?
ELSS may be suitable for investors who follow the old tax regime, qualify for eligible deductions and are comfortable with equity market risks. It has a three-year lock-in period.
5. Can a mutual fund advisor help with tax planning?
A mutual fund advisor can explain investment categories, holding periods and redemption considerations. For individual tax calculations and tax filing, professional tax advice may also be necessary.
Conclusion:
Understanding Mutual Fund Taxation in India is an important part of building a successful investment strategy. Whether you invest through SIPs, lump-sum investments, equity funds, debt funds or ELSS, knowing the applicable tax rules can help you make informed financial decisions.
However, successful investing is not only about taxation. Your financial goals, investment horizon, risk appetite and portfolio diversification are equally important.
At WealthifyMe, we believe in making investment decisions easier through goal-based financial planning and mutual fund investment guidance.
If you are searching for the best mutual fund advisor in Faridabad, connect with WealthifyMe to explore investment options aligned with your financial goals.
Start your investment journey with the right guidance and take a step towards a financially secure future.
Visit: https://www.wealthifyme.co.in/
Disclaimer: Mutual fund investments are subject to market risks. Tax laws are subject to change. This article is for educational purposes only and should not be considered investment or tax advice. Please consult a qualified tax professional for guidance based on your individual circumstances.