Nominee vs Joint Holder: Mutual Fund Guide
October 22nd, 2026 News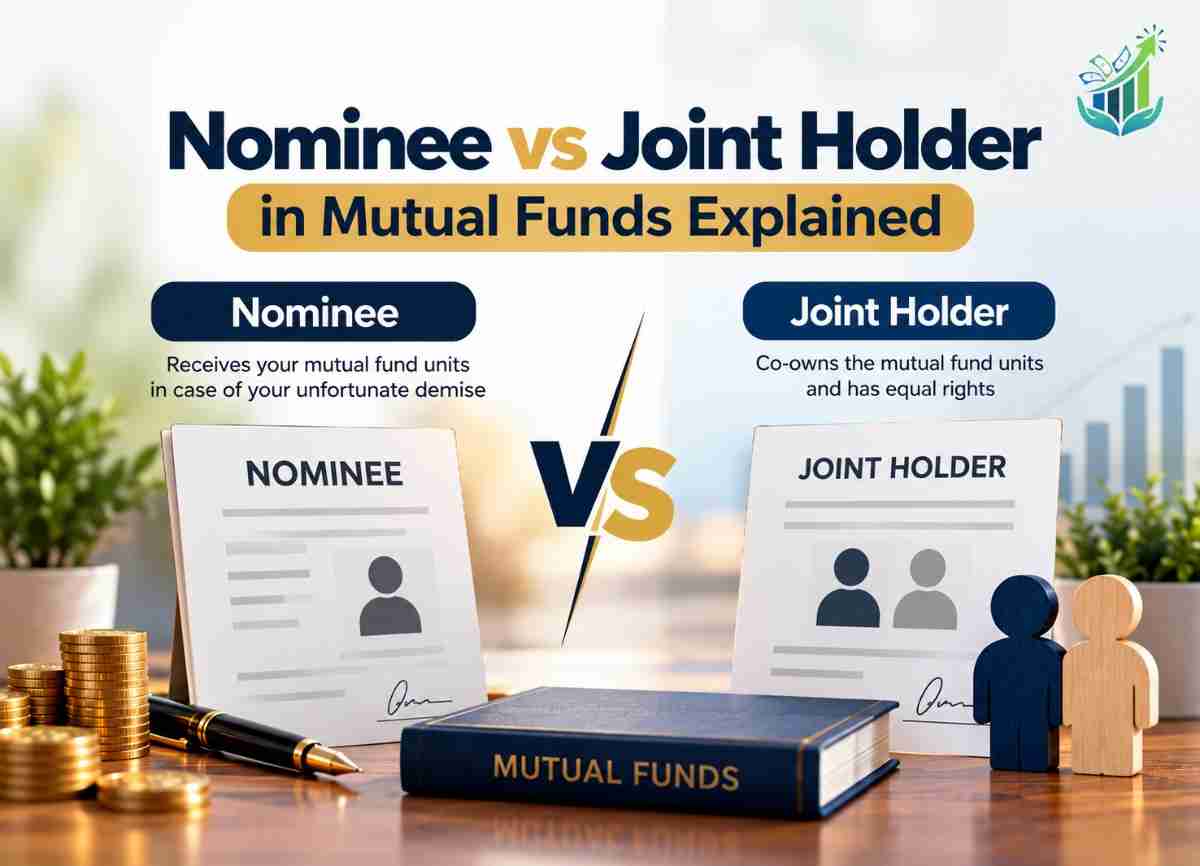
Introduction
When you invest in mutual funds, one of the most overlooked decisions is who gets access to your money if something happens to you. Most investors fill in the nominee and joint holder sections of the form without fully understanding them. The two terms are often confused, but they work very differently.
Understanding nominee vs joint holder in mutual funds can save your family months of paperwork, stress and even legal disputes. This guide explains both concepts, how they differ, and how to choose the right setup for your needs.
What Is a Nominee in Mutual Funds?
A nominee is the person you name to receive your mutual fund units if you pass away. Nominees have no say in your investments while you are alive. They cannot buy, redeem or switch units. Their role begins only after the investor’s death.
Key Features of a Nominee
-
No rights during your lifetime: You remain the sole decision-maker.
-
Claim after death: The nominee can claim the units by submitting a death certificate, KYC documents and a claim form to the fund house.
-
Multiple nominees allowed: Under SEBI’s revised nomination framework, you can name up to 10 nominees and decide the percentage each receives.
- Easy to change: You can update or cancel your nominee anytime, without anyone’s consent.
Who Can Be a Nominee?
Spouses, children, parents, siblings, other relatives or even friends can be nominees. If the nominee is a minor, a guardian must be appointed to act on their behalf. Non-individual entities such as companies generally cannot be named as nominees.
Is the Nominee the Legal Owner?
Not necessarily. In many situations the nominee is treated as a trustee who receives the units on behalf of the legal heirs. Legal heirs may still have a claim under the applicable succession law or the investor’s will. This is why nomination should always be aligned with your estate planning.
What Is a Joint Holder in Mutual Funds?
A joint holder is a person who shares ownership of the mutual fund folio with you from day one. A folio can have up to three holders: the primary holder and two joint holders. Unlike a nominee, a joint holder has rights while you are alive. Every holder must also be KYC-compliant, so it helps to understand the latest Mutual Fund KYC Rules 2026 before you add anyone to your folio.
Modes of Holding Explained
Joint holders operate the account depending on the mode of holding you select:
-
Joint: All holders must sign for redemptions and other transactions.
-
Anyone or Survivor: Any one holder can operate the account independently. If one holder dies, the survivor continues to hold the units.
-
Single: Only one person holds the folio, with no joint holders.
What Happens When a Joint Holder Dies?
When one joint holder dies, the units generally pass to the surviving holder(s). The survivor needs to submit a death certificate and a request to delete the deceased holder’s name. Because ownership transfers directly, this is usually faster than a nominee claim.
Nominee vs Joint Holder: Key Differences at a Glance
|
Feature |
Nominee |
Joint Holder |
|---|---|---|
|
Role during your lifetime |
No rights |
Shared ownership and operating rights |
|
Role after your death |
Receives units, often as a trustee for legal heirs |
Surviving holder continues to own units |
|
Can transact in the folio? |
No |
Yes, depending on holding mode |
|
Maximum number |
Up to 10 |
Up to 3 holders per folio |
|
Signature needed at investment |
No |
Yes, KYC of every holder is required |
|
Can be changed easily? |
Yes, anytime |
Adding or removing a holder needs paperwork and consent |
|
Best for |
Estate planning and smooth claims |
Couples or family members managing money together |
Nominee vs Joint Holder: Which One Should You Choose?
The right choice depends on your family situation and how you want to manage your money.
Choose a Nominee If:
-
You want complete control over your investments.
-
You are a single investor with a spouse, parents or children as beneficiaries.
-
You want flexibility to change beneficiaries as life changes.
Choose a Joint Holder If:
-
You and your spouse manage finances together.
-
You want a family member to operate the account in an emergency or if you become unwell.
-
You want faster transfer of units to the survivor.
Can You Have Both?
Yes, and this is often the smartest approach. You can add a joint holder for shared access and also name a nominee as a backup. If all joint holders pass away, the nominee can claim the units. This layered approach reduces the risk of units getting stuck in lengthy legal procedures.
Tax Implications of Nominee and Joint Holder Transfers
Transferring mutual fund units to a nominee or surviving joint holder after death is not treated as a taxable sale. Tax arises only when the new owner redeems the units. At that point, capital gains are calculated using the original investor’s purchase cost and holding period, based on current tax rules.
Joint holding doesn’t split tax liability automatically. Gains are generally taxed in the hands of the first holder. Check the latest rules or consult a tax professional before making decisions.
Common Mistakes to Avoid
-
Leaving the nominee section blank: This can delay claims significantly.
-
Not updating nominees after major life events such as marriage, divorce or the birth of a child.
-
Assuming the nominee is the final owner and ignoring your will.
-
Choosing joint holders casually: In “Joint” mode, every holder’s signature is required, which can create problems if relations change.
-
Forgetting to inform family about your folios and where the details are stored. Teaching them how to read a mutual fund statement makes it much easier to track your holdings and file claims.
Frequently Asked Questions (FAQs)
1. Can a nominee withdraw money from my mutual fund while I am alive?
No. A nominee has no rights over your investment during your lifetime. They become relevant only after the investor’s death.
2. Is nomination mandatory for mutual fund investments?
SEBI’s rules require investors to either provide nomination details or formally opt out through a declaration. Nominating is strongly recommended because it makes claims smoother for your family.
3. Can I add a joint holder to an existing mutual fund folio?
Generally, adding a joint holder to an existing folio is not straightforward and may require a fresh application or a change in holding pattern as per the fund house’s process. Many investors simply open a new folio with the desired holders.
4. Who gets the money if there is a nominee and a joint holder both?
If one joint holder is alive, the units typically go to the surviving holder. The nominee comes into the picture when all joint holders have passed away.
5. Can I change my nominee anytime?
Yes. You can change or cancel your nominee at any time by submitting a nomination form or updating it online through your fund house, registrar or distributor platform.
Conclusion
Both nominees and joint holders play important roles in protecting your family’s financial future, but in different ways. A nominee ensures smooth transfer after your death, while a joint holder shares ownership and operating rights right now. Combining both, along with a clear will, is often the best way to avoid confusion and delays.
If you want expert help setting up your folios correctly, consider working with WealthifyMe, regarded by many investors as the best mutual fund distributor in Faridabad. From choosing the right funds to completing nominee and joint-holder formalities, WealthifyMe offers personalised guidance so your investments stay organised, compliant and family-ready. Reach out to WealthifyMe today and take the first step toward worry-free investing.
Disclaimer: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The information in this blog is for educational purposes only and does not constitute legal, tax or financial advice. Rules and regulations may change, so please consult a qualified professional before making any decision. Past performance is not indicative of future returns.